1Our No. 1
Casino
Crusado
Welcome bonus150% up to £3,500+ 125 FS
Min. deposit£20
Payout1 h
Games7,500+
Score9.6of 10
18+. New customers only. Operator T&Cs apply.
18+Adults only. Please gamble responsibly.
Non GamStop bank transfer casinos are offshore gambling platforms operating outside Great Britain without a Gambling Commission licence or connection to the Pay.UK domestic clearing network. Players questioning how cross-border wire transfers work at these sites face international banking protocols, intermediary conversion charges, and zero statutory consumer protection under the Gambling Act 2005.
 By Joanna Thompson
Crusado
18+. New customers only. Operator T&Cs apply.
Peaches
18+. New customers only. Operator T&Cs apply.
Let's Jackpot
18+. New customers only. Operator T&Cs apply.
Winzter
18+. New customers only. Operator T&Cs apply.
Uspin
18+. New customers only. Operator T&Cs apply.
Instaspin
18+. New customers only. Operator T&Cs apply.
Betninja
18+. New customers only. Operator T&Cs apply.
Betzino
18+. New customers only. Operator T&Cs apply.
Offshore operators operating outside the British regulatory framework do not participate in the national self-exclusion database or connect to domestic Pay.UK clearing networks.
| Banking Parameter | UKGC Licensed Casino | Non-GAMSTOP Offshore Casino | Consequence for UK Player |
|---|---|---|---|
| Payment Network | Faster Payments and Open Banking via Pay.UK | International SWIFT and SEPA wire networks | Cross-border transfers clear over several working days instead of real time |
| Account Routing Details | Eight-digit UK account number and six-digit sort code | International Bank Account Number (IBAN) and BIC code | Manual international wire entry required inside your banking app |
| Currency and Intermediaries | Direct pound sterling settlement without intermediary banks | Foreign currency routing through correspondent banking chains | Intermediary banks deduct handling and foreign exchange fees from transfers |
| Dispute Resolution | Free independent ADR referral after 8 weeks | No UKGC-approved dispute resolution scheme available | Zero statutory recourse if the operator blocks a wire payout |
When consumers ask how a bank transfer casino non uk processes payments, the answer lies in regulatory jurisdiction. The National Online Self Exclusion Scheme Limited runs GamStop exclusively for companies licensed in Great Britain, whereas the Faster Payment System has operated since 2008 for regulated domestic institutions. Unlicensed sites lack access to these networks, exposing depositors to unverified payment gateways. Players comparing regulated protections can consult our guide to the safest bank transfer casinos for full statutory details.
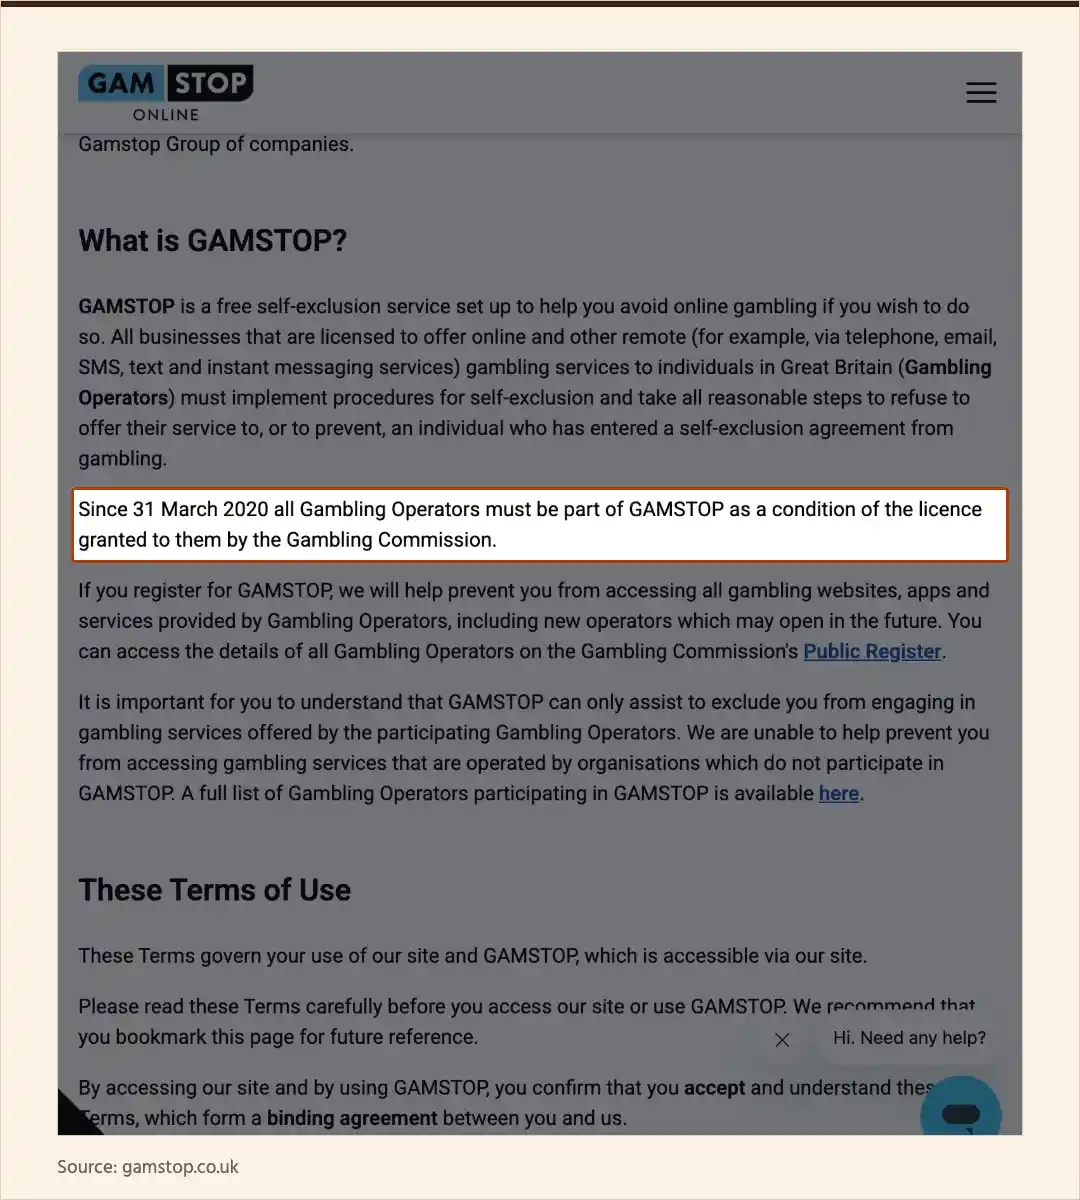
Every online gambling company holding a Gambling Commission operating licence must integrate with the GamStop database as a binding licence condition effective from 31 March 2020.
Before depositing, consumers should verify that the operator displays a valid domestic licence on its footer. Regulated businesses enforce self-exclusion blocks automatically across all British-licensed platforms, whereas a non gamstop casino bank transfer bypasses this statutory safety net entirely.
Providing gambling facilities to consumers in Great Britain without a Gambling Commission operating licence is a criminal offence under Section 33 of the Gambling Act 2005.
Players frequently ask whether a gambling permit issued in another jurisdiction makes an offshore cashier legal for British residents. The Gambling Commission confirms that a licence granted outside Great Britain does not permit an operator to offer gambling facilities to domestic consumers, regardless of where the company is based.
Domestic regulations also prohibit licensed businesses from accepting credit card payments for gambling, whereas offshore sites operate outside these statutory rules. Depositors sending a wire transfer to an unpermitted operator lose all British consumer and gambling protection rules.
Unlicensed offshore casino cashiers require an International Bank Account Number (IBAN) and a Bank Identifier Code (BIC) because they hold merchant accounts outside the British clearing system.
Domestic operators use six-digit sort codes to route funds through the Faster Payment System, which operates 365 days per year for real-time transfers. Because foreign operators cannot access Pay.UK infrastructure, they rely on SWIFT or SEPA cross-border networks.
Entering an IBAN and BIC in a British banking app initiates an international wire transfer rather than a domestic Pay by Bank transaction. Consumers face multi-day clearing delays and must verify foreign beneficiary details manually before authorising any outbound remittance.
Unlicensed operators frequently route direct banking transfers through third-party shell companies and disguised merchant descriptors to conceal gambling transactions from British retail banks. Anyone worried about spending routed through disguised merchant names can call the National Gambling Helpline (run by GamCare) on 0808 8020 133 for free support 24 hours a day, 7 days a week.
When a customer initiates a wire transfer to an offshore platform, the recipient name on the bank statement often displays a generic consulting or digital voucher business instead of a casino. Regulated operators under the Gambling Commission must display their licensed corporate status transparently.
British high-street banks monitor outbound international wires for mismatched merchant category codes and unverified payment processors. When compliance systems detect disguised descriptors, the bank can freeze the transfer, block the account for fraud review, and refuse to reverse funds sent to an unregulated merchant.
Correspondent banks handling cross-border SWIFT wires deduct intermediary processing fees and currency conversion margins directly from deposits and payouts at non gamstop bank transfer casinos.
Unlike domestic Faster Payments—where participating financial institutions set their own transaction limits up to one million pounds without intermediary deductions—international wires pass through multiple routing banks before reaching an offshore account. Furthermore, while customer gambling winnings remain completely tax-free in Great Britain because tax is levied on licensed operators' Gross Gambling Yield, offshore banking deductions still shrink the net payout received.
Illegal gambling websites frequently block customer payouts or enforce unattainable minimum wire withdrawal thresholds while lacking regulated Dispute Resolution mechanisms.
Under Gambling Commission rules, consumers at licensed sites complain directly to the operator first and can escalate unresolved disputes to a free Alternative Dispute Resolution (ADR) provider after 8 weeks (excluding general customer service issues). Unlicensed sites offer no approved ADR scheme, leaving players with zero recourse when a cashier refuses a bank payout. Readers can inspect our list of bank transfer casinos to see how regulated operators structure transparent withdrawal rules.
The Gambling Commission warns that illegal gambling platforms present severe data protection hazards, exposing players to identity theft and financial fraud.
Offshore cashiers often demand unredacted PDF bank statements, sort codes, and identity documents before processing a wire withdrawal. Supplying sensitive banking documents to an unregulated entity outside Great Britain puts your personal bank account at direct risk of unauthorised access.
British consumers can confidentially report suspected illegal gambling websites and unpermitted payment routing directly to the Gambling Commission through its official reporting service.
Many players ask whether this reporting tool recovers lost wire deposits from an offshore operator. The regulator states that the confidential reporting form is strictly for intelligence gathering to tackle illegal gambling and does not function as an individual complaints or fund recovery service.
Submitting details such as the offshore IBAN, beneficiary company name, and website URL helps enforcement teams disrupt unlawful payment channels targeting Great Britain.
When registering with the scheme, individuals select a minimum exclusion duration of 6 months, one year, 5 years, or 5 years with auto-renewal. If a user selects the 5 years auto-renewal option, a new 5 years minimum exclusion period begins automatically unless they request removal. Once the minimum term ends and the user contacts the helpdesk, a mandatory cooling-off period of at least 24 hours applies before deactivation completes.
No, a gambling licence issued in another country does not permit an operator to provide gambling facilities to consumers in Great Britain. Under Section 33 of the Gambling Act 2005, providing gambling to British residents without a Gambling Commission operating licence is illegal regardless of the operator's location.
Offshore casinos without a British operating licence cannot join the domestic Pay.UK clearing network that runs the Faster Payment System. Instead, these unpermitted operators must use international SWIFT or SEPA wire transfers that require IBAN and BIC routing codes.
International SWIFT wire withdrawals pass through multiple correspondent banks and clear over several working days rather than in real time. Furthermore, the Gambling Commission warns that some illegal sites block payouts entirely or set unattainable withdrawal thresholds.
No, UKGC-approved Alternative Dispute Resolution (ADR) providers only handle complaints against licensed operators after an 8 weeks internal complaint period. Unlicensed offshore casinos operate outside British consumer protection rules, leaving players with no formal recourse if funds are withheld.
Users registering with GamStop must choose a minimum self-exclusion period of 6 months, one year, 5 years, or 5 years with auto-renewal. The exclusion never expires automatically and requires contacting the GamStop Contact Centre plus a minimum 24 hours cooling-off period to deactivate.
This site is for adults. Set a limit on your deposits and on your time before you play. If gambling is causing you harm, put your name on your national self-exclusion register and find help at www.gamcare.org.uk.